debtcare.ca

Author: mgoldenberg@debtcare.ca

  • On the Cheap: Free or Cheap GTA Family Activities

    Summer is fast approaching and that means it is time to start planning those family activities and adventures. Yes, we know the summer can become really expensive, really quickly, when you add up all the things you want to do. If you’re looking for something to do that won’t cost an arm and a leg, we’ve compiled a list of fun and free or cheap GTA family activities you can do.

    Free or Cheap GTA Family Activities

    • Become one with nature. Head to the Allan Gardens and take your time winding through the flowers and plants. Admission and limited parking are free.
    • Head to the market. Check out the bustling St. Lawrence Market, the city’s largest market, fill your picnic basket with great local fare and enjoy the entertainment as you stroll through the stalls.
    • Get active. Head out to one of the many public parks in the city. Bring a ball and glove for some catch, a Frisbee or a good book.
    • Get your hands dirty. Head to Riverdale Farm in Cabbagetown. This 7.5-acre facility is a working farm, complete with cows, horses, sheep, pigs and chickens, vegetable gardens and a farmer you can chat with as he does his chores.
    • Head to the beach and cool down. Don’t want to rely on the A/C to keep cool? Head to one of the many beaches the city has to offer. Head to Cherry Beach or Bluffers Beach Park, lay down your towel or spark up a game of volleyball. If it gets too hot, just take a dip!
    • Channel your inner artist. Visit the Art Gallery of Ontario and peruse the permanent collection. Admission is free on Wednesday nights from 6 to 9 PM.
    • Get historical. There are a ton of great museums located throughout the GTA. Every Thursday between 5:00 and 8:00 PM, admission is pay-what-you-can at the Bata Shoe Museum. Shoes not your thing? Drop by the Toronto Police Museum and Discovery Centre and check out stuff like old weapons, uniforms, fingerprinting equipment, and a paddy wagon from 1914. Admission is free seven days a week, even on holidays.
    • Catch a free concert. Several different locations throughout the city offer free concerts and performances all summer long. The Canadian Opera Company, Yonge and Dundas Square, Harbourfront, and Mel Lastman Square are all great places for free entertainment.
    • Get your brew on. If you’re a fan of craft beer, take a free tour of the Amsterdam BrewHouse. Tours take place Monday to Thursday at 5:00 PM and on Fridays at 11:00 AM.

    Summer doesn’t have to break the bank. These free or cheap GTA family activities make it easy.

    If you’re looking for some help getting your finances in order to make summer more stress-free, DebtCare can help.

    Get in touch with us today by calling 1 (888) 890-0888.
     

  • Will a Creditor Actually Sue You When You Default on a Debt?

    We often have clients call us, when debt becomes unmanageable, asking if a creditor will actually sue if you default on a debt. While it may seem unlikely, it is, unfortunately, very common.
    A creditor may sue you themselves, hire a paralegal to cover it, or assign your account to collections, whereby the collection agency may sue you. If a judgement is secured against you, they can then take enforcement action to obtain the funds owed.

    Enforcement action may include a wage garnishment, a property lien or a frozen bank account.

    All of these are embarrassing and could have other consequences.

    A wage garnishment not only reduces your income (as the money is taken from the source to pay the debt), it also lets your employer know that you have a financial problem. This is particularly problematic for those in jobs where you have to be financially responsible. If you’re self-employed, the notice of garnishment is sent to your clients and intercepts their payments to you, letting them know that you’re financially in trouble. This can damage your reputation.

    A lien on property will effectively mean that you can’t refinance the asset and could mean additional fees and financial consequences to get the lien discharged when it is paid. It will also make the creditor a secured creditor, thus reducing financial options should you decide to file a consumer proposal or a bankruptcy.

    Not only will a frozen bank account result in an inability to access funds, it can damage your relationship with your bank. This may result in them choosing to suspend other credit products, make changes to your account (i.e. removing an overdraft), or deciding not to extend credit to you in the future.

    If a creditor is threatening to sue you, you need to take action now. Waiting will often just result in one of the above.

    If you find yourself worrying about such things, the first question to ask is why you are in this situation to begin with. Do you have financial challenges making it hard to pay your debt? Perhaps you just need a fresh start.

    A consumer proposal is a great way to consolidate debt and:

    • Stop collection action – even a lawsuit or enforcement action from a judgement (as long as it’s not a lien)
    • Stop interest
    • Reduce debt in most cases
    • Consolidate everything into a single monthly payment

    If you owe and your creditor is threatening to take you to court, don’t assume that this is an empty threat. Once legal action is initiated, you may find yourself in much deeper financial waters.

    At DebtCare, we can help you deal with your debt before it gets to this point, or, if it has already reached this point, help you stop that enforcement action.

    Call us today 1 (888) 890-0888.


  • What is a Licensed Insolvency Trustee (LIT)?

    When you’re researching your options for getting control of your debt, you may find yourself confused by the vast array of terms out there – both for the options and the people who provide and manage them. This week, in an effort to clear some of the confusion, we are covering one crucial term – Licensed Insolvency Trustee.
    A Licensed Insolvency Trustee (LIT) is a federally regulated professional who provides advice and services to those with debt problems. They are authorized to administer government-regulated proceedings, such as consumer proposals and bankruptcies.

    Often, when individuals start thinking about their options for dealing with problem debt, a bankruptcy trustee or Licensed Insolvency Trustee is the first person who comes to mind. However, there is the misconception that a trustee represents you. While a trustee does represent your interests, they are also representing your creditors’ interests. Their role is to negotiate a satisfactory arrangement for all involved.

    Therein lies the problem. Once you provide information to your trustee, under the assumption that it is private, the trustee will then structure your bankruptcy accordingly (this is what they are required to do). Any information you provide is fair game and will be used to get the largest payout for your creditors. Furthermore, in the case of a consumer proposal, your Licensed Insolvency Trustee is paid based on the size of the proposal. This means that a larger proposal amount equals more revenue for them – there is no incentive to get you the best deal.

    If you are struggling financially and are considering a consumer proposal or bankruptcy to help you regain control, the best thing you can do is speak with a financial consultant with experience helping people deal with problem debt.

    Such a person, hired by you to represent you and only you, will review and structure your financial information based on that review and a realistic plan that you can afford. They will then present a solution to a trustee they know and trust, one they’ve had past dealings with, and co-ordinate the process and help you throughout.

    When you’re drowning in debt, there are many benefits to bankruptcy or a consumer proposal. Both represent an important resource, you just need to be sure that the person standing beside you is actually concerned about your financial welfare.

    At DebtCare, we know how best to protect you. Instead of heading straight to a Licensed Insolvency Trustee.

    Call us first. We represent you. 1 (888) 890-0888.


  • Dealing with Income Tax Debt – What Happens if You Owe?

    The income tax filing deadline is April 30th, and that means, if you owe a tax debt to the Canada Revenue Agency (CRA), you may be wondering what happens when you owe and how long you’ve got before the CRA will start asking for their money.
    Firstly, failing to file is never a good idea, even if you know you will owe. Failing to file will result in penalties and interest, as well as possible enforcement action. These add up quickly. If you haven’t filed yet, try to do so soon.

    Furthermore, not filing may be considered tax evasion. At the very least, you may be notionally assessed, meaning the government will estimate your income and then assess penalties and interest. The worst-case scenario, if you choose not to file, is that you could be prosecuted.

    If you file and owe a tax debt, you’re in a better position because you won’t have those added penalties and you won’t face prosecution. However, the CRA won’t wait for years to pass before attempting to collect. We have seen taxpayers’ accounts frozen within the current tax year. For example, one taxpayer filed on time, owed $3000, and had their account frozen the following January.

    A tax debt is a financial problem that should be addressed quickly – you can’t wait around hoping for the best. There really is no ‘best’ here.

    The CRA will want to be paid in full. Agents are not interested in making negotiated settlements or agreeing to long-term payment plans. That just isn’t how they operate, no matter how dire your situation is. If you don’t have the money on hand to pay in full, here are some of your financial options:

    • If you have good credit, you may want to consider obtaining a line of credit or loan from the bank. This option will rely on your ability to repay that debt, but on more reasonable terms. However, if you are already loaded with debt, it may not be the best solution because the interest is higher on unsecured credit.
    • Use home equity to finance the tax debt. This is typically the lowest interest option but you will need a home and some equity to take this route.
    • A consumer proposal. This is a no-interest option that will offer a low monthly payment and will sometimes even reduce your amount of total debt. There are some implications to credit to be considered, but if you’re already drowning in debt it could represent the best financial option overall.

    The best way to deal with a tax debt you can’t pay in full is to speak with a financial consultant who understands all of your available options. Don’t go directly to the CRA as this will result in far fewer possible choices and things could become even more problematic as far as repayment.

    At DebtCare, we can walk you through all of your options and get that tax debt off the table.

    Call us today for a free consultation: 1 (888) 890-0888.


  • By the Numbers: What is a Bad Credit Score?

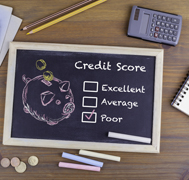
    Your credit score is very important. It represents how lenders perceive you as far as risk and impacts how likely you are to obtain various credit products. If you’re concerned about your credit, you may be wondering what a bad credit score is – and so today’s blog should help you better evaluate your own situation.
    A consumer credit score, also known as a FICO score or Beacon score, ranges from 300 to 900. According to TransUnion, a score above 650 will likely qualify you for a standard loan while a score under 650 will typically make receiving new credit difficult. These are the typical ranges:

    • 750+ Excellent
    • 680+ Good
    • 600-680 Fair
    • Below 600 is not good

    One of the quickest ways to get a bad credit score is to default on your current debts. Missing even one payment can be detrimental. Also, if you have defaulted on numerous accounts, you may not actually remember everything you’ve missed (phone bills, utilities, and other products that are not loans and credit cards), meaning they often get lost in the shuffle, further impacting your credit score.

    Building great credit takes work, but breaking down that great credit can be swift and long-lasting. Once credit has been destroyed, you may want to throw your hands up in the air in defeat, but don’t give up –recovering from bad credit is not as painful as you might think.

    If you’re ready to rebuild, there are certain steps that you can take to get the process started. Begin by getting your credit report to better understand what’s listed there and what you owe. Get it from both credit reporting agencies – Equifax and TransUnion.

    The next step, and arguably the most important step, is to deal with past debt. Obviously, if you had the money to pay these past due balances, you would have done so, but ignoring them further just exacerbates the issue. Speak to a financial consultant who specializes in this area to get support concerning options to clear bad debts.

    While dealing with a bad credit score and rebuilding credit, a secured credit card is a great way to build things up.

    Also, remember not to repeat past bad habits. As you rebuild credit, don’t max out new credit, make late payments or go crazy applying for credit everywhere. These are all red flags for lenders and work towards bringing that credit score back down. Try to keep your limits at 50% of your available credit (or less) and make more than the minimum monthly payments.

    At DebtCare, we understand how difficult it can be when you’re sitting with a bad credit score. If you’re struggling to deal with your debt, we can help.

    Call us today for a free consultation: 1 (888) 890-0888.


  • Are You Ready for Canadian Mortgage Interest Rates to Go Up?

    Currently, Canadian mortgage interest rates are at record lows. This has been great for those looking to obtain mortgage financing over the last few years, whether first or second mortgages. However, as the saying goes, nothing lasts forever.

    Back in March, CTV News reported that experts are warning of a rise thanks to U.S. bond prices. According to the article, “Fixed rate mortgages, the most common in Canada, are tied to long-term Canadian bond prices, which are in turn tied to U.S. bond prices. Banks sell bonds to raise money to lend to mortgage holders and other borrowers. When the U.S. Federal Reserve raises rates, bond prices typically fall. As bond prices fall, banks tighten their lending, and mortgage rates rise.” This could mean hikes for Canadians looking to refinance their current mortgages.

    Read more on this here: http://www.ctvnews.ca/business/mortgage-expert-warns-u-s-fed-will-cause-rate-increases-in-canada-1.3322093.

    If mortgage rates rise, many Canadians could be in trouble, especially those with high levels of debt. For example, if five-year fixed rates were to rise from 2.5% to 3% on a $300,000 mortgage, that would result in an almost $80 increase to each monthly payment. An increase to 3.5% would represent almost $150 more per month. Can you afford an increase of $80 a month? What about $150?

    Using your mortgage to get your debt in order is a great way to prepare yourself should Canadian mortgage interest rates rise. Doing so can help get rid of the various monthly payments, leaving you with one monthly mortgage payment. This will greatly reduce interest and should help you better manage on a monthly basis. But you have to act quickly.

    Start by finding out what your home is actually worth and verifying how much equity you have to play with. These two numbers will help you determine the refinancing option best suited to your situation, be it a first mortgage, a personal line of credit, or a second mortgage.

    Even if you have bad credit, having enough equity could put you in a much better financial position, helping to restore your credit and getting rid of some of that stress caused by the debt.

    Using your home to refinance and consolidate debt is a great financial option, but you need to strike while the iron is hot. It is best to lock in at the current low rates before things get more expensive.

    DebtCare offers a free, fully-customized, property valuation report and mortgage refinancing advice to help you make the most prudent financial decision.

    Get in touch today by calling 1 (888) 890-0888.


  • 信 用 報 告 在加拿大的重要性, DebtCare为你解答更多相关信息

    信 用 報 告 在加拿大的重要性, DebtCare为你解答更多相关信息

    信 用 報 告 在加拿大的生活中非常重要, DebtCare Canada 很乐意助你 信 用 報 告 解释上的内容和潜在问题, 继续阅读下去有关 信 用 報 告和’信用查询’的博文。

    每當你申請信貸,無論是貸款、銀行借款、汽車貸款或是信用卡,與你合作的金融機構會要求進行一次信用調查。這有助於他們更好地了解你的支付能力和判定你的信貸習慣是否會造成潛在風險。

    請記住不單是向你開放借貸的公司,其他公司或機構也可能會獲得你的信用報告。開設一個新的銀行賬戶或者申請工作都有可能引起一次信用調查。

    當一間公司要進行信用調查和查詢的時候,他們會聯繫一所信用報告機構並請求一份你的信用報告的複印件。屆時,日期、債權人名字和債權人電話號碼都會被記錄在冊。重要的是你需要知道這些請求都會顯示在你的信用報告上,而且如果顯示太多信用調查的次數,這可能對整體信用分數造成負面影響。

    '信用报告'
    信用报告, 信用查询, 信用调查, 信用分数


    舉例說,如果你的報告上顯示你一年內有多於4次信用調查請求,這會讓你給人感覺是一個四處找尋借貸機會的人──意味著你需求借貸。

    如果你已經走訪過多於一所機構和多次進行信用調查,也可能表明了你在申請信貸的時候遇到困難。

    關於信用調查,有太多重要的事情需要注意了。即使你從沒打算使用那些信用卡,也不要相信那些贈送你免費禮物的信用卡申請陷阱,因為這些信用調查的記錄仍然會顯示在你的信用報告上。


    如前所述,過多的請求次數會影響你的信用評分並引發一個“多次請求信用調查”的信息出現。

    兩類請求會被列明在信用報告上──軟性請求和硬性請求。

    軟性請求就是與你合作的債權人進行的信用調查用於對你申請的某些項目進行預審(例如更高的信貸額度),或者當你申請查閱自己的信用報告。

    硬性請求就是當你同意進行一次信用調查,比如當你申請一種新的信貸產品(貸款、汽車借款和銀行的信用額度)。

    這些公司都必須得到本人的同意才可以進行信用調查,所以時時都要確保清楚明白你所同意的是什麼。

    你可以通過 Equifax  https://www.consumer.equifax.ca/personal/products/credit-report/ 或 TransUnion  https://www.transunion.ca/product/credit-report  購買查詢自己的信用報告。

    了解你所處的信貸消費立場,同時保持你的信用得到適當控制是非常重要的,因此請確保關於你的任何信用調查都是極度需要才讓它實行。

    浏览我们的博客获取更多关于信用报告和债务重组的信息。

  • 如何处理债 务(二)- 赌 债

    如何处理债 务(二)- 赌 债


    在加拿大,赌债 在某程度上跟流感没什么两样,都是像传染性病毒一样。如果你不幸在加拿大背上 赌债,不要对自己失去信心。沉溺上瘾相当于一种病,而 赌博 就是让人高度上瘾的东西。如今,进入加拿大的赌场比以往任何时候都更轻易。从你赢钱的那一刻起,兴奋和愉悦早已蒙蔽了你,让你当下觉得赌博根本不是有害的活动,但是你往往无法想象,它即将变成严重改变你人生的劣瘾。

    当 赌博 习惯开始引起生活破碎,人们才开始意识到问题的严重性。财务上来说,赌博成瘾会导致损失收入、资产的潜在损失、生活水平大大降低,甚至可能失业。个人角度来说,赌博成瘾会导致伴侣间的矛盾争执,还有朋友的家人的疏离。

    赌博成瘾也可能引发健康问题。你也许正受到不同健康状况的困扰,包括高血压、消化系统紊乱、压力和忧虑,抑郁甚至产生自杀倾向。

    加拿大电视台最近报道过一份加拿大统计局的研究,较富裕的人群往往有能力下较大的赌注,但对于某部分赌徒来说,他们所挣的钱并不多,却将大部分的收入都压在赌博活动上。

    而根据加拿大电视台的报告,加拿大统计局的研究显示6.3%的人被认为是“危险赌徒和问题赌徒”。问题赌徒占了加拿大总人口的0.6%,也就是大约180,000人次。加拿大统计局对于问题赌徒的定义就是在游戏中经常是输家,而且每年进行不少于五次的赌博活动。

    赌博, 赌债, 债务, 欠债


    参与赌博的人应当:

    • 看作普通娱乐项目而非收入性活动
    • 均衡地多参加其他活动
    • 不要独自进行赌博
    • 将输掉的钱看作花销在娱乐项目上的消费
    • 设定一个合理的预算并坚持在预算内进行赌博
    • 千万不要借钱去赌博
    • 为自己设定赌博的时限(规定自己在x小时内离场)
    • 在赌博期间进行多次休息,让头脑和心态保持理智


    如果你由于赌博问题已经背上 债 务 ,那么你必须站起来与问题对抗。因为即使还没发生,但你已经把自己推到了将失去一切的境地了。在加拿大有很多援助和支持开放给身陷 赌债 的人群。这些援助不但帮助他们戒掉赌瘾,也帮助他们处理因赌瘾而累积的沉重 债 务。

    其中一些办法包括参加诸如匿名戒赌互助会这样的组织,将自己从赌博活动中抽离,并善用博彩责任委员会的自我戒赌工具,同时积极寻求专业的财务规划指引。千万不要将物业转至至亲的名下,也不要在原有债务基础上借更多的债。

    加拿大有很多开放的项目可以帮助赌徒妥善处理 赌债,通过擅长处理 债 务 的顾问专家,你可以获得很多相关处理 债务 的信息,并成功申请以解决 债 务 难题。

    你并非唯一一个为了 赌债 而烦忧的人,数千加拿大人都有着同样的问题,很多人都看到了希望也成功走出困境,我相信只要你愿意,数百种解决方案都在等着你。


    浏览我们的博客获取更多关于信用报告和债务重组的信息。

  • 如何处理债务 (一) 被追债公司催收的债务

    如何处理债务 (一) 被追债公司催收的债务

    在加拿大,很多人有被追债公司催收债务的经历。追债公司经常受雇于私人商业机构或部分银行,他们负责追讨被拖欠已久的债务。当某一公司将有欠债的客户账户指派给追债公司,追债公司会收取欠债人的服务费用和额外的利息,使得债务数目飞速增加。

    某些追债公司会用到每天打几次电话到你家或公司的手段;而其他的追债公司也许已经从债主处获得小额法庭的申请判令,对你采取法律强制收债措施。追债公司在你的信用报告上递交“被催收项目”,这将对你的信用造成相当大的危害;然而,如果你已经有拖欠未付的借款或信用卡债务,你早已损害了自己的信用。无论从哪个角度看,在加拿大要处理这些被催收的债务绝对不是一件乐事。

    追债公司被委任催收的债务并不只是普通的借款和信用卡债务。如果你拖欠了水电费账单、电话费、健身俱乐部会员费、拖车服务账单、交通罚款等,这些债务都有可能会由追债公司负责追收。

    好消息是,在加拿大的大部分省份,追债公司是受管制的。也就是说,你拥有你的权利!以安省为例,消费者服务厅通过“收债公司法令”管制追债公司。你可以在E-Laws网站上浏览安省收债公司法例。如果追债公司在追讨债务时行为过分越界,你可以向消费者服务厅投诉并申请对此严加管制。部分省份接受网上投诉,有些省份则要求你将投诉信和证据一同寄到相关部门。

    如果你是由于不擅长应对债务而导致债务被转至追债机构,与其直面这些追债行动,不如在众多解决方案中找到一个适合你自身状况的办法进行解决。很多项目都提供可以解决债务和停止收债行动的援助。

    面对债务时可能会导致沉重压力和夫妻关系紧张,很多人都认为摆脱债务的唯一办法就是申请个人破产。事实并非如此,其实有另一项处理债务的方案不但可以冻结利息为0%,而且能助你得到债务的部分减免。

    面对债务时,最坏的决定就是置之不理。因为这样做只会延长你信用被破坏的时间,而且债务只会随时间过去而不断增加,而非自行消失。越早处理好债务,你的信用和财务状况就越早得到重建和修复。尽快将这段债务堆积的日子结束并抛诸脑后吧!

    如需了解更多关于如何处理债务和应对追债公司的资讯,请通过浏览我们的主页debtcare.ca/chinese或致电1-866-260-9672联络DebtCare Canada。

  • Trying to Negotiate with the CRA is a Dangerous Game

    We are officially reaching the end of the 2017 tax season, and that means that most Canadians have completed filing and many are patiently waiting for their refund cheque in the mail. If, however, you’ve yet to file because you know a tax debt is headed your way, or have filed and have your assessment in hand, you’re probably at the other end of the spectrum. Your first thought may be to call the Canada Revenue Agency directly and attempt to negotiate a payment plan, but we urge you to read on and reconsider that approach. Trying to negotiate with the CRA is a dangerous game – one that can land you in a heap of financial trouble.

    The CRA is well-known for their oft-nefarious tactics for collecting what they believe is owed. When you have a tax debt, the CRA is not interested in a long term payment plan with low monthly payments, and this is primarily why it is so dangerous to call.

    When you initially call the CRA to negotiate a payment plan, things may not seem so bad. Agents are encouraged to cultivate a ‘friendship’ with you in the hopes that you will willingly share as much financial information as possible. This is usually accomplished with a financial disclosure form. In this form you’ll be asked questions about your income, where you work, where you bank, where you live and your current financial obligations. Don’t be fooled – the CRA is not asking for this information to help create a payment plan that suits your current financial situation.

    Once you’ve provided this information, the CRA may agree to accept a temporary payment plan, but once this payment plan expires, that ‘friendship’ will also expire. Now that the CRA has all of your financial information, the new payment plan will take into account none but the most basic living necessities (all other creditors will be subtracted from the equation) and you’ll be facing a monthly payment far and above what you can reasonably afford to pay.

    What if you don’t pay? Thanks to that financial disclosure form, not paying isn’t really an option. Not only does the CRA now know all about your finances they also know where you work, bank and live, making wage garnishments, frozen bank accounts and property liens that much easier to obtain.

    So, if you shouldn’t be calling to negotiate directly with the CRA, what options are available? Unless you can pay the debt in full, speak with a financial consultant to discuss the various options available to clear the debt before enforcement action is levied against you. Once this happens, things are going to become much harder to navigate.

    At DebtCare, we know how difficult the CRA can be to deal with. We also know how to protect you when it comes to dealing with a tax debt.

    Get in touch today by calling 1-888-890-0888.